
As fears of ‘no-deal’ rise, I’m opting for a staycation next year
Can CIMB turn local relationships into a connected ASEAN wealth franchise?
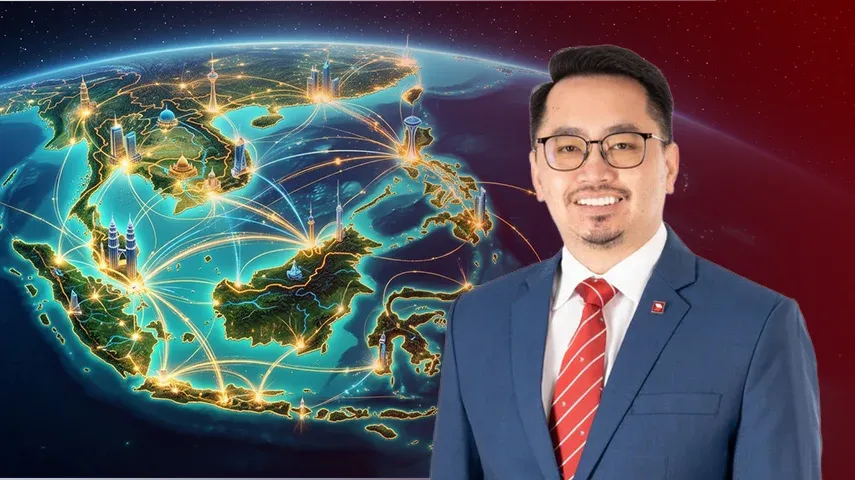
CIMB is building its wealth strategy around longstanding local customer relationships across its core ASEAN markets. Its opportunity is to deepen those relationships through advice, connect customers' personal and business needs across borders, and extend them across generations.
Southeast Asia's growing wealth pool is becoming increasingly regional. Entrepreneurs may build businesses in one country, hold investments and property in another, educate their children overseas and maintain financial relationships across several jurisdictions. For banks with regional networks, the opportunity is therefore not simply to gather more assets from increasingly affluent customers, but to make those networks work as connected financial relationships.
CIMB Group is attempting to do this as it expands its wealth franchise across Malaysia, Indonesia, Singapore and Thailand. CIMB Private Wealth was launched in Indonesia in January 2026 and Malaysia in July, extending a customer continuum that already runs from its Preferred affluent franchise to private banking.
Haniz Nazlan, Chief Executive Officer of Group Consumer Banking at CIMB Group, said total customer assets across the franchise stood at approximately MYR 350 billion ($82 billion), comprising deposits, investments and bancassurance. Across its four core wealth markets, CIMB measures wealth penetration as investment and bancassurance assets as a proportion of customers' total assets with the bank, including deposits. Haniz put this at about 35% to 40%, although the proportion varies by market.
The franchise is growing. Excluding Thailand, which Haniz described as undergoing a transformation and effectively establishing a new baseline, wealth assets under management (AUM) in Malaysia, Indonesia and Singapore grew by between 10% and 30% year on year. Haniz said net new money was contributing more to growth than market movements, with investment net new money increasing by more than 20% year on year.
But growth alone does not establish what differentiates CIMB's wealth proposition. Haniz acknowledged that products can be replicated, competitors can establish investment offices and banking networks can be expanded. He argued that CIMB's distinction lies instead in the quality of the customer relationships it has accumulated in its core markets and its ability to extend those relationships across businesses, countries and generations.
Deepening relationships rather than adding segments
CIMB's starting point is its existing customer franchise. Preferred, Private Wealth and private banking serve customers at different levels of wealth and complexity, but Haniz described them less as isolated businesses than as parts of a customer relationship that should evolve as financial circumstances change.
Haniz said Private Wealth AUM is already growing faster in percentage terms than Preferred AUM, which he viewed as early validation of CIMB's proposition for customers whose needs sit between its Preferred and private banking offerings.
The bank’s Malaysia franchise added approximately 2,000 affluent customers and increased AUM by approximately MYR 1 billion ($235 million) in the first month following the launch of Private Wealth on 20 July 2026.
That distinction matters. Introducing another wealth tier does not by itself deepen a banking relationship. CIMB is therefore identifying customers within its existing mass affluent and Preferred franchises with the potential to move into Private Wealth while simultaneously looking beyond consumer banking to entrepreneurs and business owners already served elsewhere in the group.
Haniz said CIMB's consumer and commercial businesses had previously operated more independently. The bank is now deliberately identifying overlaps between its affluent and business banking customer bases, tracking referrals and connecting business owners' commercial relationships with their personal banking and wealth requirements.
This creates another route into wealth management. Instead of acquiring the entrepreneur only as an investment customer, CIMB can potentially connect deposits, financing, treasury, investments, insurance and personal wealth around an existing business relationship.
Haniz did not present an ever-rising wealth penetration ratio as the objective. Customers can move between deposits and investments as market conditions and risk appetite change. The broader aim is to deepen engagement and make CIMB the customer's primary financial institution rather than simply increase the number of affluent accounts opened.
That changes the growth logic of the strategy. The opportunity lies not only in adding wealth customers, but in progressively serving more of the financial requirements of customers CIMB already knows.
Turning local relationships into regional connectivity
The next step is extending those relationships across borders. Haniz acknowledged that regional presence alone is difficult to defend as a differentiator. Products can be replicated, branch networks can be built and competitors can establish their own chief investment offices. He argued that CIMB's difference comes from longstanding customer relationships in markets where its retail franchises are deeply established locally.
Regional connectivity then becomes an extension of the customer's home-market relationship. Haniz defined this in practical terms: customers should be able to access banking and wealth capabilities across the countries in which they live, work, invest or have family interests. That includes onboarding and servicing as well as payments, foreign exchange, deposits and investments, delivered through digital channels, branches and relationship managers.
The relationship can also extend beyond the individual. For entrepreneurs and wealthy families, regional connectivity may involve personal banking, family requirements and business interests across several markets.
Singapore already provides one indication of how this works. Haniz said about 20% of CIMB Singapore's retail customers are from Malaysia, Indonesia or Thailand, with Singapore operating as a hub for some of these relationships.
CIMB is also connecting specific financial requirements across jurisdictions. Haniz cited Malaysian customers purchasing US dollar-denominated legacy plans in Singapore and using borrowing against the policy to finance them. He said the structure could take advantage of comparatively lower borrowing costs in Singapore. Overseas mortgage financing through CIMB's Singapore franchise provides another cross-border use case.
The significance of these examples is not the individual products themselves. They show how CIMB intends regional connectivity to work: a customer relationship established in one market can provide access to financing, investments, currencies or wealth solutions available through another part of the franchise.
The model therefore remains anchored locally even as the customer's financial life becomes more regional. Rather than moving the entire relationship to a single offshore centre, CIMB is attempting to retain the home market relationship and connect additional regional capabilities around it.
Making advice the organising layer
Broader product access creates another challenge: preventing the relationship from becoming increasingly product-led as more capabilities are added.
CIMB's advisory model also sits on a product-manufacturing capability that draws on both the group and external strategic partners. Haniz said the consumer business works closely with CIMB's wholesale treasury franchise to respond to changing customer requirements, while partnerships extend its manufacturing capabilities. He cited Sun Life in bancassurance and CIMB's strategic relationship and equity ownership in Principal Asset Management as examples, saying these relationships allow the bank to develop more bespoke or exclusive propositions.
One example is Sun Save Invest Takaful, developed and managed by Sun Life Malaysia Takaful and exclusively distributed through CIMB. Haniz described it as an investment-linked takaful solution that accepts participants up to age 85, with a short contribution period and protection extending up to age 99. The product also incorporates legacy-planning features through its Legacy Inheritance & Family Empowerment (L.I.F.E.) feature, allowing participants, subject to applicable criteria, to choose how death benefits are distributed to beneficiaries.
CIMB has made its regional Chief Investment Office (CIO) one of the organising mechanisms for its wealth proposition. The regional office develops house views, asset-allocation strategies and investment playbooks across Preferred, Private Wealth and private banking. Local CIO and advisory teams then work with relationship managers to execute these views in individual markets.
Haniz described the strategy as regional by design but locally executed. There are early indications that customers receiving this advice are deepening their relationships with the bank. Haniz said AUM among customers who underwent portfolio reviews with the CIO office and investment advisers had grown 4% more than among customers who had not gone through the process.
Haniz also said AUM among CIMB's top Private Wealth clients, who have direct access to chief investment officer Patrick Chang, had grown threefold. When asked to clarify the figure, he said he meant about three times the original amount rather than a 300% increase.
These are early internal indicators rather than evidence across the entire franchise, but they provide a measurable connection between CIMB's advisory approach and deeper asset relationships.
CIMB is also translating CIO views into investment propositions. Its Signature Series provides strategies for different risk profiles, including income, growth and Sharia-compliant approaches. The bank said the range had accumulated more than MYR 2 billion ($470 million) in AUM since its launch in October 2024.
The more important organisational feature, however, is how CIMB is attempting to separate advice from product sales.
Haniz said the CIO office does not carry sales-target key performance indicators because its role is to provide advice without being driven towards particular sales outcomes. Frontline relationship managers still have commercial and AUM targets, but these sit within balanced scorecards that also measure the overall customer relationship and engagement rather than simply individual product sales.
Product-disclosure and suitability requirements are embedded in customer journeys, while Haniz said CIMB also applies controls intended to prevent unsuitable products, including sophisticated structured products, from being offered to vulnerable or less sophisticated customers.
These operating arrangements provide a more substantive measure of CIMB's move towards an advisory-led model than the breadth of its product shelf alone. They attempt to align investment views, adviser incentives and customer suitability around the total relationship rather than individual transactions.
Islamic wealth is also being incorporated into this broader advisory architecture. Haniz said many non-Muslim customers are receptive to Islamic investment solutions, particularly investment products, provided their performance is comparable with conventional alternatives. CIMB therefore starts with customer needs and preferences while offering both conventional and Sharia-compliant solutions.
The Signature Series already includes a Sharia-compliant strategy. MyWealth also allows customers to indicate that they want only Sharia-compliant investments, after which recommendations are restricted accordingly.
CIMB said more than 50% of its affluent AUM in Malaysia was Sharia-compliant as at July 2026, giving Islamic wealth an established role within its broader advisory proposition.
Scaling advice through digital capabilities
The harder problem is extending that advisory model across a much larger customer base. CIMB can provide high-touch CIO and investment-adviser engagement, but scaling the wealth franchise requires elements of that capability to reach a much broader customer base.
The bank is approaching this from both sides of the relationship. For relationship managers, a digital tool bringing together customer information, CIO insights and portfolio-management capabilities is already live in Indonesia. Haniz said CIMB is now working to replicate it in Malaysia.
For customers, MyWealth within CIMB's OCTO platform begins with risk profiling. Customers are classified according to risk appetite and shown an asset allocation based on CIO recommendations before being presented with relevant investment funds.
CIMB said unit trust sales through MyWealth had grown nearly sixfold year on year, and the platform accounted for more than 6% of the bank’s total unit trust sales over the reporting period.
Artificial intelligence could extend this model further, but those capabilities are not yet deployed at the level Haniz described.
CIMB is exploring the use of AI to review portfolios continuously, generate recommendations as circumstances change and personalise the information presented to individual customers. Haniz gave the example of a Malaysian customer regularly remitting money to a child studying in Australia. Behaviour and exposure could eventually allow the bank to provide more relevant Australian dollar insights and foreign-exchange information.
Haniz described these capabilities as work in progress and did not commit to an implementation timetable. CIMB has centralised its AI capabilities at group level and is building the underlying foundations.
The distinction is important. CIMB's current proposition already combines human advice, CIO portfolio construction and digital execution. AI represents a potential means of increasing the scale and personalisation of that model rather than an existing substitute for relationship managers.
Extending the relationship across generations
As customer wealth increases, the relationship also moves beyond investment accumulation. CIMB already provides will-writing services, including Sharia-compliant wasiat, through external partners. Haniz cited As-Salihin as its strategic partner for the Sharia-compliant service, with referrals integrated into the CIMB customer journey. Its private bank has an in-house trust capability for more complex high- and ultra-high-net-worth requirements.
CIMB is developing a broader legacy and estate-planning proposition with a law firm partner to bring together financial, legal and succession planning. It is also developing zakat and faraid calculators to help clients estimate their Islamic charitable obligations and understand estate distribution under Islamic inheritance principles.
The bank is simultaneously developing the relationship managers expected to handle those conversations. Haniz said CIMB puts relationship managers through a six-month structured development programme combining formal training with experiential learning, including exposure to asset and fund managers and other industries. The bank also draws on industry practitioners and its partner ecosystem, with Haniz citing Principal as one partner helping to train frontline staff. Relationship managers can also undertake financial planning and estate planning certifications as they progress towards serving customers with more complex requirements.
The progression is intended to mirror the customer relationship itself: more experienced advisers with larger asset relationships move into increasingly complex client situations.
CIMB is already applying this relationship model across generations of the same family. Haniz said some relationship managers cover grandparents, parents and children rather than treating every family member according to separate segment structures.
A relationship manager can therefore remain with a customer who moves from Preferred into Private Wealth when continuity across the family relationship makes that appropriate.
This becomes increasingly important as wealth transfers between generations. Older customers may require preservation, protection, estate and succession solutions, while younger family members may expect much more digitally enabled relationships.
Haniz said CIMB is working on connecting those requirements so that the relationship can continue across generations. He again characterised the proposition as still developing rather than a mature capability.
Building one relationship across businesses, borders and generations
CIMB's emerging wealth model is not based on a single capability that competitors cannot reproduce. Haniz himself acknowledged that products, distribution networks and CIO capabilities can be replicated. His proposition is that CIMB starts with something accumulated over a longer period: established customer relationships in its core ASEAN markets.
The strategy is using those relationships in several directions. Customers within the existing affluent franchise can move into deeper wealth relationships as their assets and needs become more complex. Entrepreneurs can connect their business and personal financial requirements. Home-market relationships can provide access to capabilities elsewhere in CIMB's regional network. Wholesale treasury capabilities and strategic partners can broaden the solutions available to those customers, while CIO-led advice can organise a wider range of investments around portfolios rather than transactions and digital capabilities can extend elements of that advice to more customers.
The relationship can then extend further as customers' needs move from wealth accumulation into protection, estate planning and succession, and as the bank begins serving the next generation of the same family.
Several parts of the model remain under development. Private Wealth itself is relatively new in Indonesia and Malaysia, CIMB is still working to scale high-touch CIO and investment adviser engagement across a broader customer base, more complex legacy capabilities are still being built and the customer-facing AI applications Haniz described remain work in progress.
What is already clearer is the organising logic. CIMB is using its local customer relationships as the anchor for connecting more of each customer's personal wealth, business interests, cross-border requirements and family needs. Its regional network matters not simply because it gives CIMB a presence in multiple ASEAN markets, but because it provides the platform through which those existing relationships can be extended across them.
Keywords: Wealthy Families, High Net Worth Individuals, Affluent Banking, Digital Wealth Platform, Succession Planning, Cimb Wealth Management, Asean Wealth Management, Cross-border Wealth Management, Wealth Advisory, Islamic Wealth Management, Digital Wealth Management
Institution: CIMB Group, CIMB Private Wealth, CIMB Preferred, CIMB Private Banking, CIMB Islamic, Sun Life Malaysia Takaful, Principal Asset Management, As-Salihin
Country: Malaysia, Indonesia, Singapore, Thailand, Australia
Region: Asia Pacific, Southeast Asia
People: Haniz Nazlan, Patrick Chang


Leave your Comments